The Weekly: The Path to Easier Financial Conditions
NOV 16, 2026
BTC wicks to $62k on forced selling as the dollar stalls. Why tight financial conditions mark a liquidity pause, not the end of the crypto bull market.
New Institutional Report, written in collaboration with Clear Street. Institutional DeFi needs a common language for risk. Led by Re7 Founder and CIO Evgeny Gokhberg and built on our own methodology, A Framework for Decomposing DeFi Risk in the Age of AI breaks exposure into chain, protocol and asset layers and explores how AI is reshaping risk monitoring.
Evgeny Gokhberg joined Alex Scott on Solana is Global “How Re7 Turned On-Chain Risk Into a Repeatable Investment Process”
🎧 Spotify
🍎 Apple
Hyperliquid is setting the pace in crypto: Hyperliquid Strategies’ David Schamis on Crypto Minutes, Bloomberg TV
Re7’s Founder & CIO Evgeny Gokhberg is joined by David Schamis, CEO of Hyperliquid Strategies, the Nasdaq-listed company building a treasury of HYPE.
They discuss how Hyperliquid’s open architecture is becoming the foundation for new markets and financial products, and why perpetual futures may offer the most efficient path for bringing real-world assets onchain.
A conversation close to home for Re7, having been involved in the Hyperliquid ecosystem since its early days.
Watch the full episode here.
Re7 Labs
Re7 Labs x Jupiter: Re7 Labs is a launch curator for the newly live Jupiter Vaults, bringing institutional-grade risk curation to Solana’s deepest liquidity layer.
We are hiring!
Senior Legal Counsel - Apply here.
Crypto Fund Operations Manager - Apply here.
Weekly Summary
We cover:
Why the liquidity slowdown is a pause, not a cycle top
The catalysts for a liquidity recovery around the new year
The Path to Easier Financial Conditions
Some weeks feel like years. Nvidia CEO Jensen Huang resigned (is he already staging a comeback in the same week?), crypto markets saw $6bn in liquidations, the FAA issued a nationwide ground stop for all flights, Deutsche Bank officially rolled out crypto custody services, and a Starship rocket was caught at its own launch tower.
Last week, we highlighted liquidity as the primary constraint on risk assets, with higher rates and a stronger dollar tightening financial conditions.
The dollar’s rally to a 19-month high has weighed on equities, gold and crypto, although it is now showing signs of exhaustion at the top of its rising channel.
Price-Insensitive Selling
That said, it felt like there was a distressed BTC seller over the weekend forcing price down to $62k, creating liquidation cascade. The result was a 3.4 sigma vol-adjusted move.
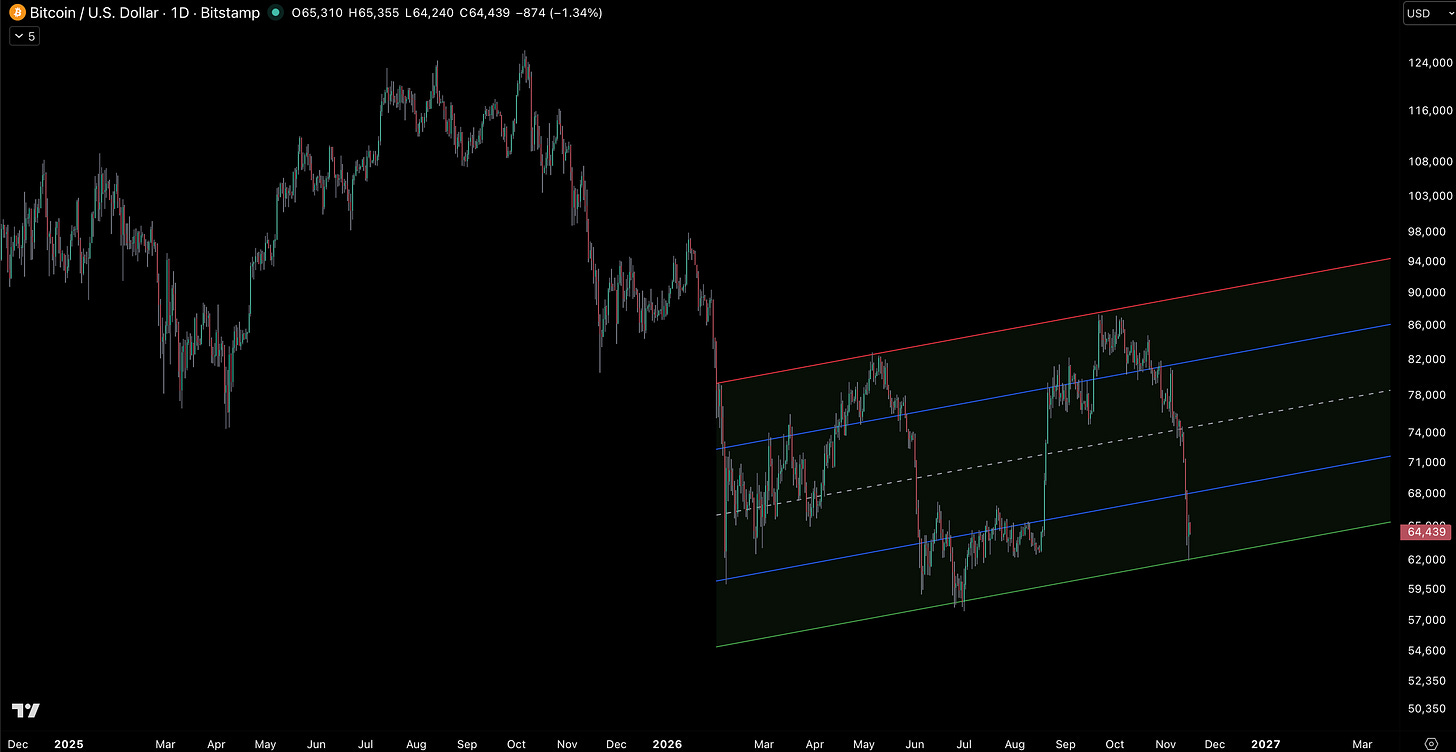
BTC/USDT (daily).
The selling was concentrated on Coinbase over the weekend, suggesting a large, price-insensitive seller needing to act fast.
The concentration of selling suggests a flow-driven dislocation rather than a broader deterioration in market fundamentals.
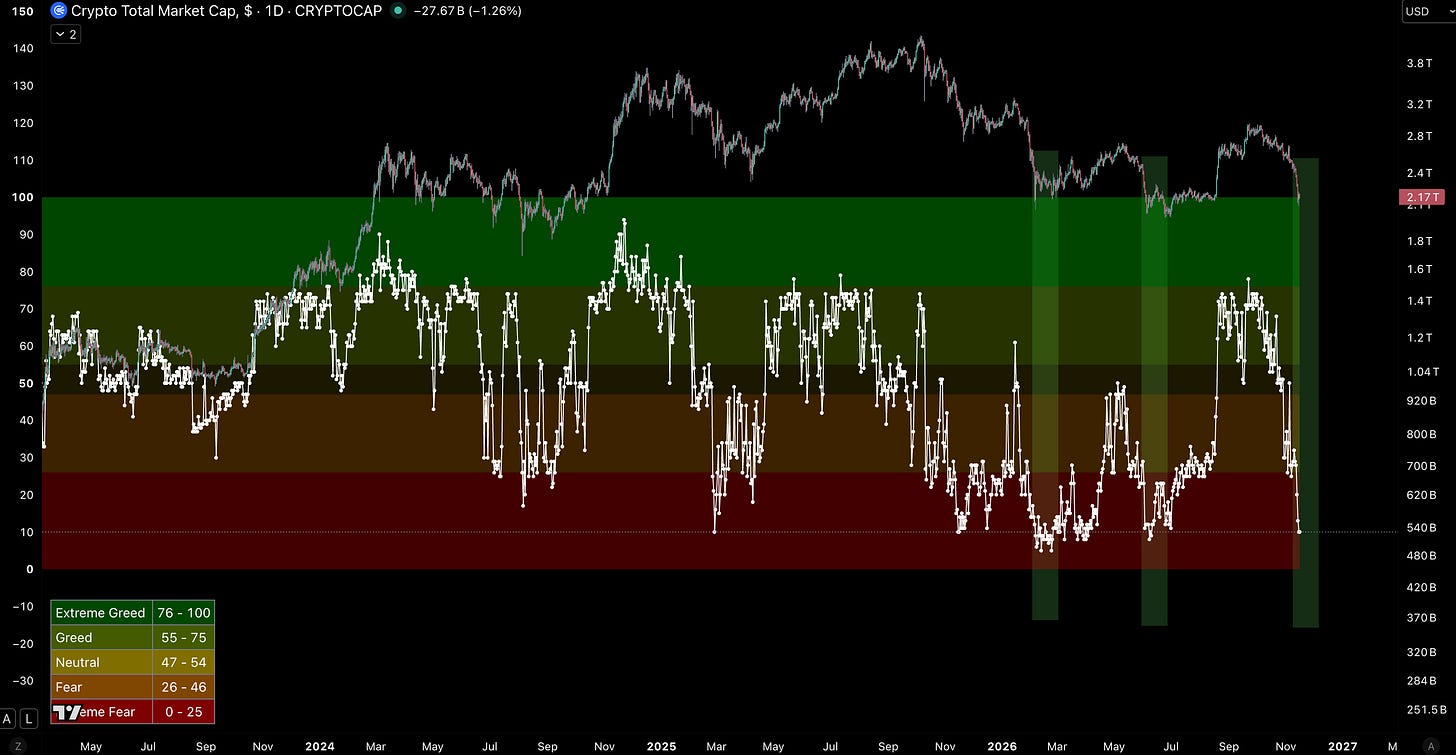
The result was crypto wicking down to its 284w MA and summer lows.
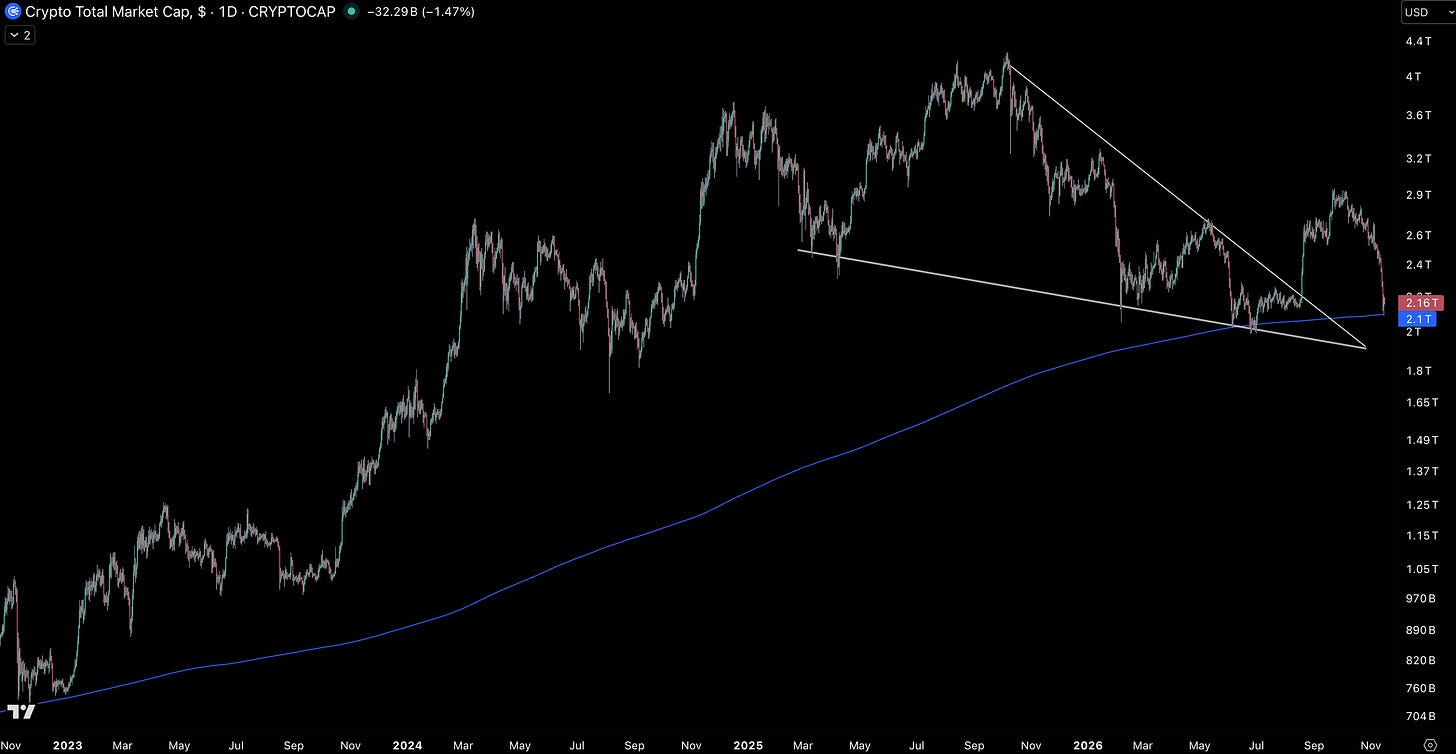
Global crypto market capitalisation index (daily).
What’s more is we’re now oversold/exhausted vs. NASDAQ.
Fear & Greed sentiment measures are now at cycle lows, with readings half those seen during the FTX collapse.
For alts, the story remains unchanged. Alts outperformed +3% vs. BTC last week.
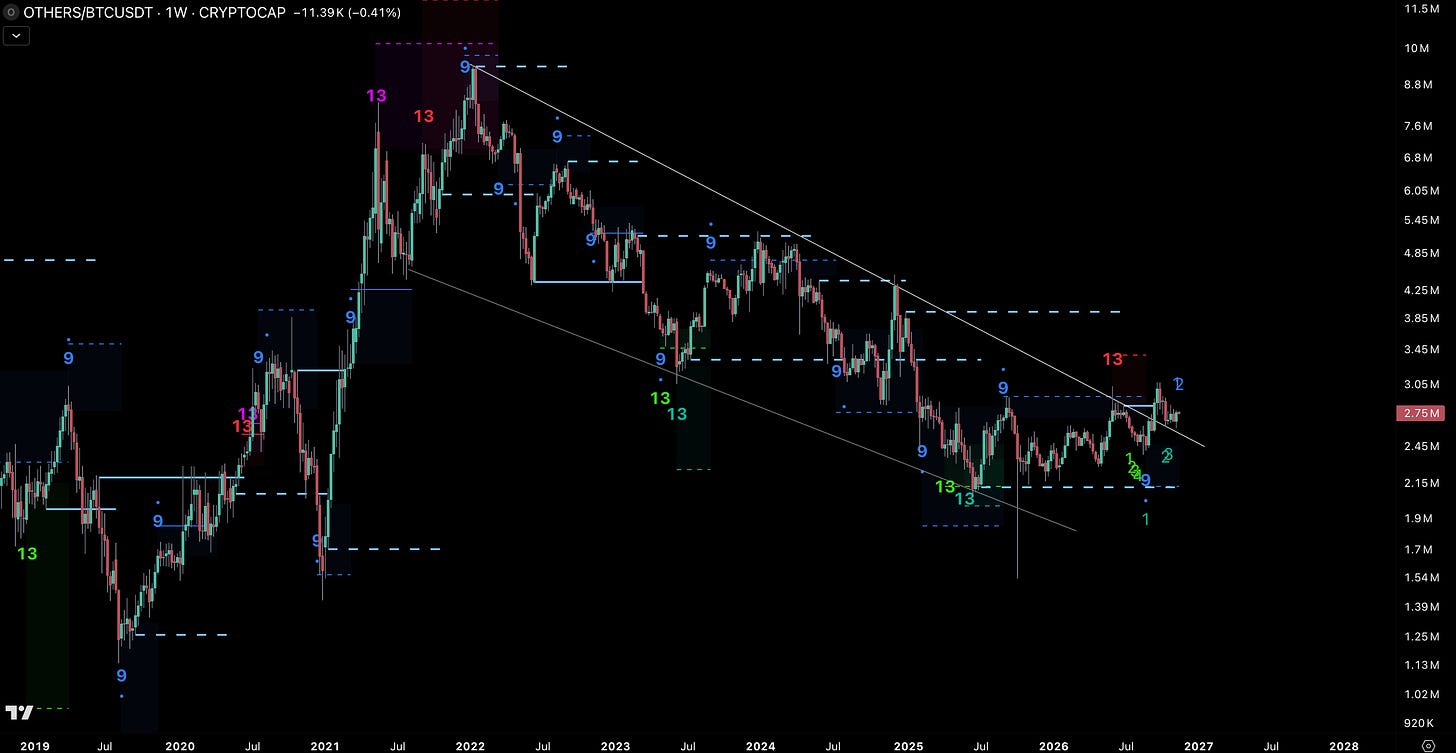
Alts/BTC ratio (weekly). Others is alts outside of top 10.
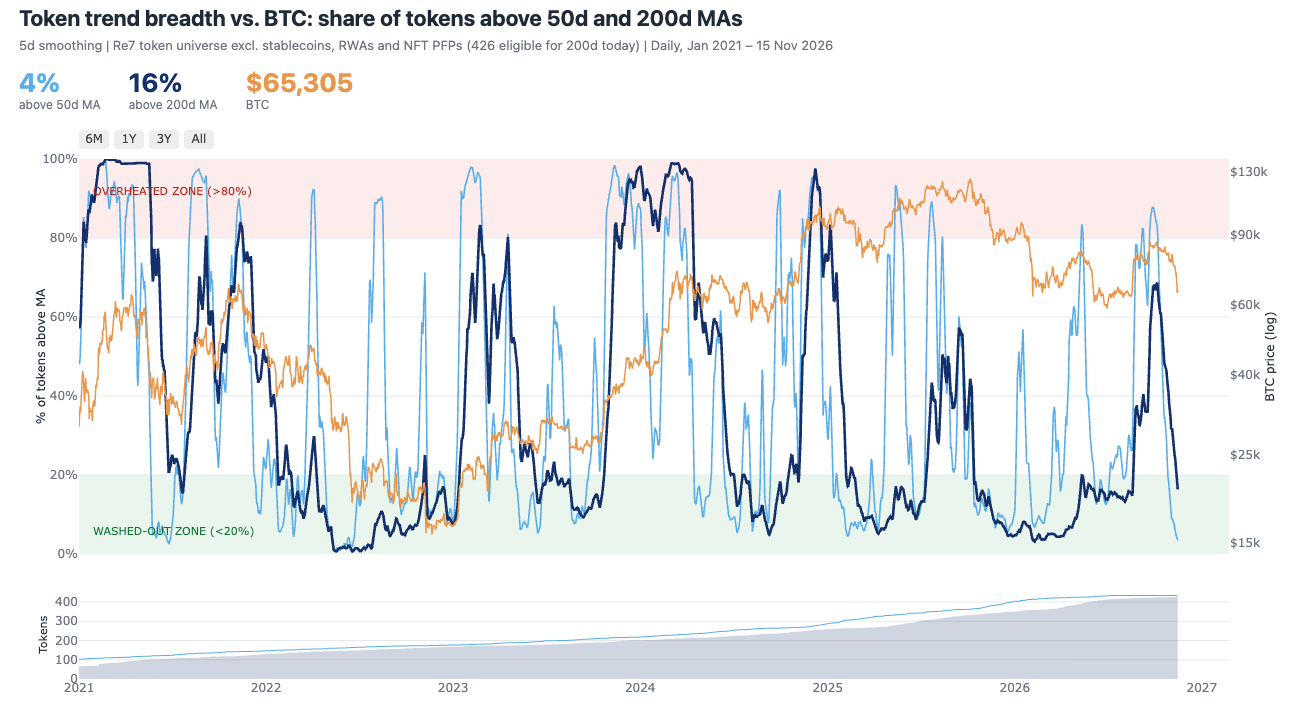
Alts have already been washed out in the prior weeks as you can see in the below chart. Only 4% of alts are above their 50d MA.
Breadth is now at historically depressed levels, suggesting much of the selling may already have played out and leaving the market increasingly sensitive to any recovery in risk appetite.
Tether dominance is approaching levels last seen in June 2023, with weekly momentum showing signs of exhaustion.
A potential top in stablecoin dominance would suggest the set up emerging broadly now is capital rotating back into alts again from what has been a very fearful 2026.
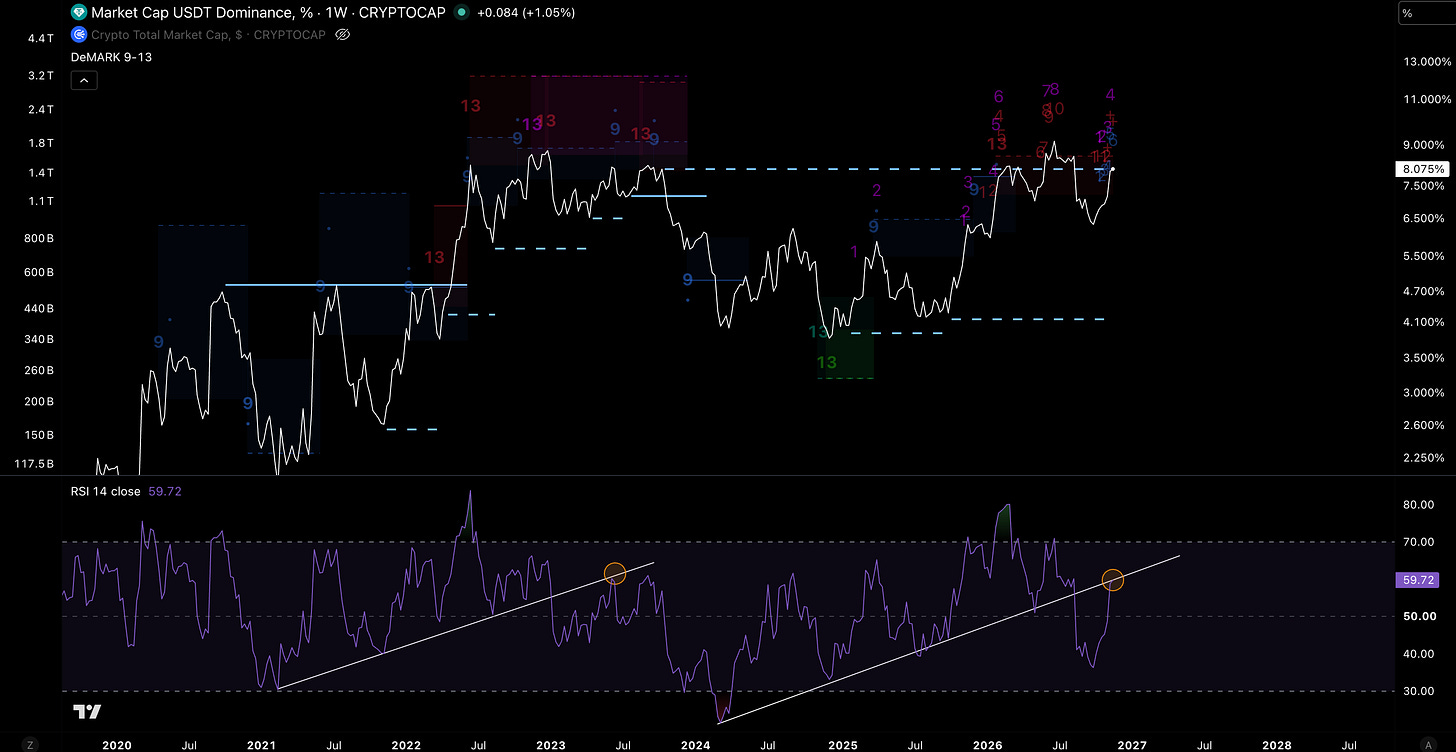
Tether stablecoin market dominance (%) and RSI.
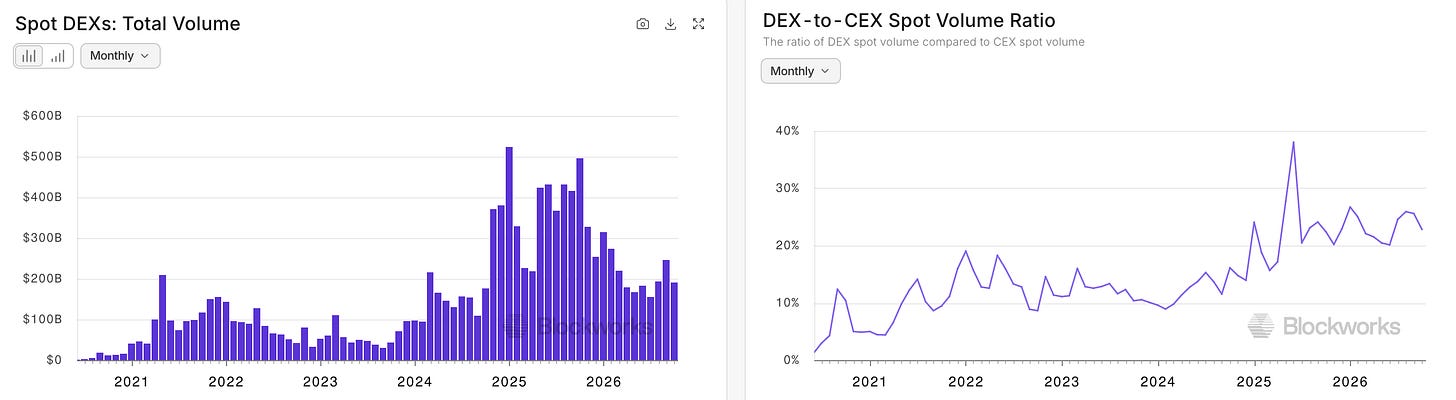
This volatility comes despite underlying sector KPIs remaining resilient, and in some cases improving.
Spot DEXs are a clear example, with the DEX-to-CEX volume ratio continuing to climb as part of a secular shift towards onchain trading. Yet, valuations of the protocols capturing this growth have compressed despite improving underlying fundamentals.
The divergence between improving adoption and compressed valuations continues to strengthen the fundamental case for selective exposure
Looking Ahead
We continue to see the recent weakness as a pause in the liquidity cycle rather than the end of the broader bull market.
Financial conditions have tightened considerably, slowing liquidity growth and weighing on risk assets, particularly crypto. Yet, the pause doesn’t need a major policy shift to end. It only needs financial conditions to stop tightening.
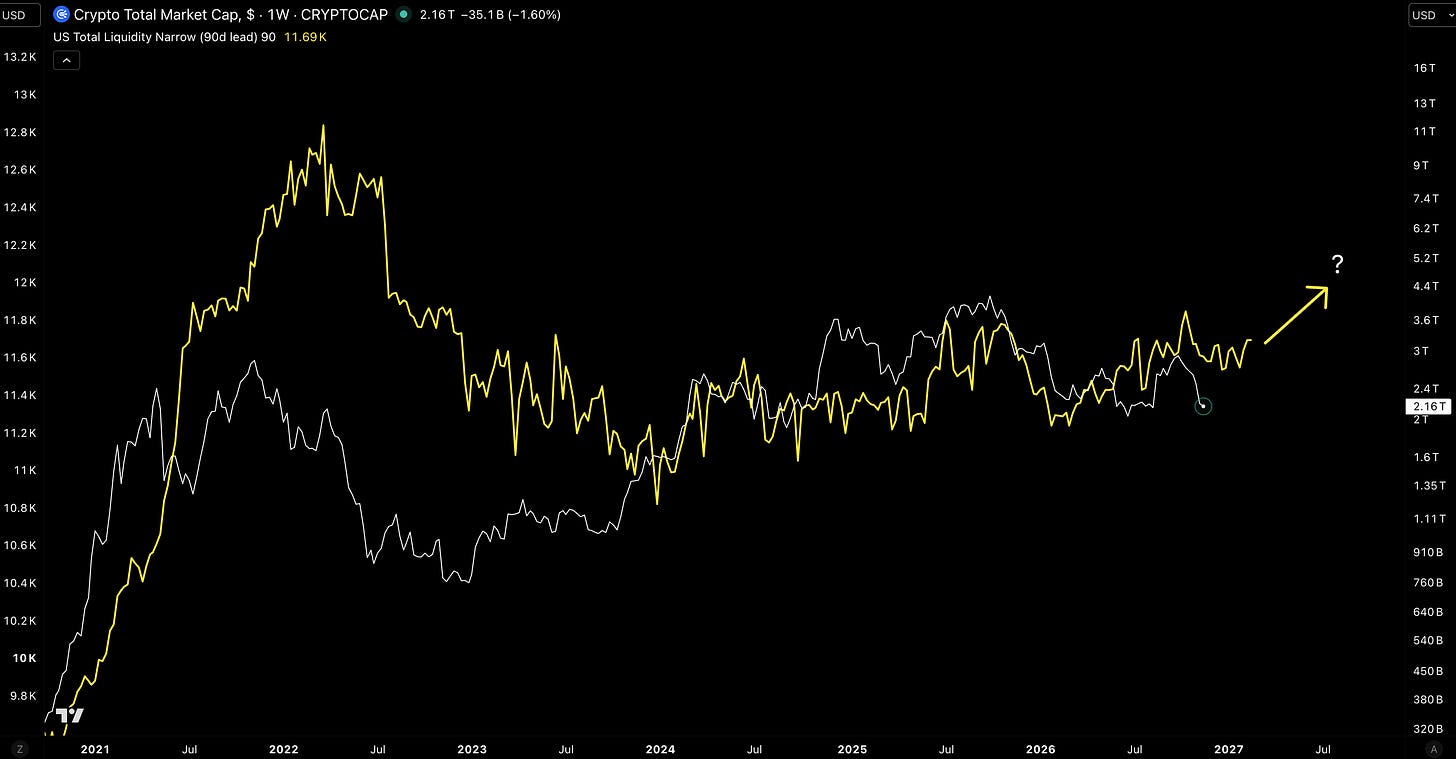
Crypto market cap vs. US narrow liquidity, the new money coming straight from the Fed and Treasury, shown with a 90-day lead. Narrow liquidity leads crypto by about three months, and Bitcoin is the asset most sensitive to it.
Lower rates and a weaker dollar would provide relief, with base effects potentially supporting a turn around the new year.
Liquidity has also become increasingly responsive to changes in financial conditions, suggesting any improvement could translate into renewed momentum for risk assets relatively quickly.
Near-term volatility could remain elevated, with Nvidia earnings and the upcoming IPO providing two potential catalysts for sharper market moves.
Both arrive against a backdrop of tight financial conditions and fragile positioning, leaving markets particularly sensitive to surprises.
The pause doesn’t need a major policy shift to end. It only needs financial conditions to stop tightening. With base effects becoming more favourable around the new year and liquidity responding more quickly to financial conditions, the next liquidity impulse may be closer than recent price action suggests.
State of Yields
Yields have expanded slightly across the board in light of recent market volatility:
Stablecoin lending yields:
~4.3% on Aave (USDC) — 60 bps higher than last week.
~5.38% on Aave (USDe) — 80 bps lower than last week.
~5.12% on Maple (syrupUSDC) — 2 bps lower than last week.
Fixed-rate DeFi lending: yield premium in fixed markets:
Pendle sUSDAi: ~8.94% (Oct 2026 – Feb 2027 maturities).
sUSDe: ~5.29%
ETH yield benchmarks:
Lido staking: ~2.77% — 50 bps higher than last week.
About Re7
Re7 Capital is a research-driven digital asset investment firm specialising in DeFi yield and liquid alpha strategies.
Re7 Labs is an on-chain asset management and risk curation firm bringing institutional-grade rigour to DeFi.
Disclaimers
The content is for informational purposes only. None of the content is meant to be investment advice. Use your own discretion and independent decision regarding investments. The opinions expressed in all Re7 public research articles are the independent opinions of the authors at the time of publication and not the opinions of the affiliates of Re7.
Please see here for full disclaimers.